
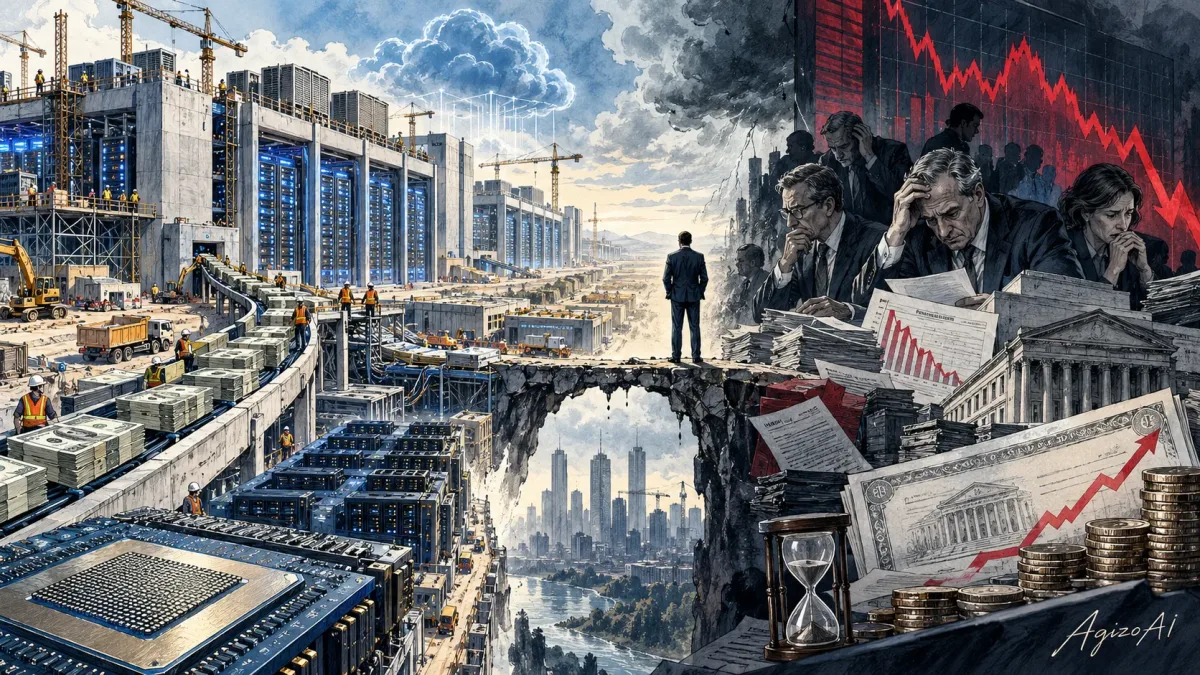
The AI Capex Backlash Has Arrived: Why Investors Are Starting to Fear the Cost of the Boom
The AI capex backlash has moved from a Wall Street talking point into a real market event.
Technology shares fell sharply after investors reacted to the rising cost of artificial-intelligence infrastructure, tighter financing conditions and growing uncertainty over how quickly enormous AI investments will produce sustainable returns.
Meta became the clearest symbol of the shift.
The company raised the lower end of its 2026 capital-expenditure forecast to between $135 billion and $145 billion. It also reported negative free cash flow of $2.12 billion in the third quarter, its first quarterly cash-flow deficit in more than a decade.
Meta shares fell sharply. The cost of insuring its debt against default reached a record high.
The wider market followed.
The Nasdaq fell 2.6% on 22 October, its steepest daily drop since early June. Semiconductor shares were hit particularly hard, while AI infrastructure names including CoreWeave, Nebius, IREN and Applied Digital came under renewed pressure.
This does not mean investors suddenly believe artificial intelligence has no future.
It means they are beginning to ask a harder question: how much capital can the AI industry absorb before returns fail to justify the cost?
AI Capex Backlash: Key Numbers
| Metric | Latest Figure |
|---|---|
| Meta 2026 capital expenditure | $135 billion to $145 billion |
| Meta Q3 free cash flow | Negative $2.12 billion |
| Meta share decline after results | More than 6% |
| Nasdaq decline on 22 October | 2.6% |
| Philadelphia Semiconductor Index decline | 6.7% |
| CoreWeave 2031 bond yield during recent stress | Above 16% before easing |
| Projected Big Tech AI and data-centre spending in 2026 | Hundreds of billions of dollars |
What Triggered the Sell-Off?
The immediate trigger was a combination of earnings reports and updated spending plans.
Investors have tolerated enormous AI budgets because revenue growth and optimism around future demand remained strong.
That tolerance is now being tested.
Meta’s latest spending plan showed just how expensive the next phase of the AI build-out could become.
The company raised the lower end of its annual capital-expenditure range by $5 billion, from $130 billion to $135 billion. The top end remains $145 billion.
At the same time, free cash flow turned negative.
That combination matters.
Capital expenditure is not automatically bad. Companies invest because they expect future returns.
But when spending rises faster than cash generation, investors start asking how long they will need to wait before the investment pays off.
Meta Has Become the Test Case for AI Spending
Meta is not the only company spending heavily on AI, but it is becoming one of the clearest tests of investor patience.
The company is building data centres, buying accelerators, expanding infrastructure and placing its Muse AI agent at the centre of its consumer strategy.
More than 10 million users in the US and Canada reportedly created Muse accounts within six weeks.
That adoption is encouraging.
The financial question is whether usage eventually produces enough revenue and margin to justify the infrastructure required to support it.
Meta’s first quarterly free-cash-flow deficit since 2012 made that debate more urgent.
Why Credit Markets Matter More Than the Share Price
The share decline attracted most of the headlines.
The credit market may be more important.
Meta’s five-year credit-default swaps widened sharply after the company increased its spending outlook.
Credit-default swaps are a form of insurance against a borrower failing to repay debt.
A higher price does not mean investors expect Meta to default.
It does show that markets are attaching more risk to the company’s financial profile.
For a company with Meta’s balance sheet, that is notable.
The AI Boom Is Becoming a Financing Story
The first stage of the AI boom was mainly a technology story.
Who had the best model?
Who had the fastest GPU?
Who could train at the largest scale?
The next stage is increasingly financial.
Who can fund enough infrastructure?
Who can borrow at a reasonable rate?
Who can generate enough cash before debt becomes expensive?
Who can keep upgrading chips without destroying returns?
Those questions are becoming central because AI infrastructure depreciates quickly.
Data centres can last for years, but the accelerators inside them can become less competitive much faster.
CoreWeave Shows the Other Side of the AI Boom
CoreWeave represents a different version of the same problem.
Meta funds much of its AI expansion from a giant existing business.
CoreWeave is a specialist AI cloud company that relies heavily on debt and external capital to build infrastructure.
That makes it more sensitive to interest rates and credit-market confidence.
CoreWeave’s shares and bonds have already come under pressure as investors question whether future AI demand will justify the cost of financing its data centres.
The company has pointed to a large contracted backlog as evidence that demand remains strong.
Yet bond investors have demanded very high yields.
That is a warning for the wider AI infrastructure market.
A company can have customers and still face financial pressure if the cost of capital rises too quickly.
Why High Interest Rates Change the AI Math
AI infrastructure is unusually sensitive to borrowing costs.
Data centres require enormous upfront spending.
The revenue arrives over time.
When interest rates rise, the gap between today’s cost and tomorrow’s payoff becomes more painful.
A project that looked attractive when financing was cheap can look much less attractive when debt yields climb into double digits.
This is one reason CoreWeave has become a closely watched indicator.
Its financing costs tell investors something about how willing credit markets are to fund the next generation of AI infrastructure.
The Semiconductor Sell-Off Matters Too
The Philadelphia Semiconductor Index fell 6.7% during the latest sell-off.
That matters because chip companies sit at the centre of the AI capital-spending cycle.
If investors become more cautious about data-centre construction, they may also become more cautious about future demand for accelerators, memory, networking equipment and manufacturing tools.
The logic is simple.
Lower expected AI spending means lower expected demand somewhere in the hardware supply chain.
Is This the Start of an AI Bubble Collapse?
Not necessarily.
Markets often correct before they collapse.
AI demand remains strong.
Cloud companies continue to report growing usage. Enterprises are deploying agents, coding systems and generative AI tools. Data-centre capacity remains tight in many regions.
The market is not saying that AI has no value.
It is saying that price matters.
A technology can transform the economy and still produce disappointing investment returns if too much money is spent too quickly.
The Dot-Com Comparison Is Useful — but Incomplete
Investors frequently compare the AI boom with the dot-com era.
The comparison has some value.
Both periods involved genuine technological change, enormous capital investment and very high expectations.
But there are important differences.
Today’s largest AI investors are already highly profitable companies with huge cash flows.
Many dot-com companies had little revenue and no proven business model.
That gives Big Tech more room to absorb mistakes.
It does not remove the risk of overinvestment.
The Real Question Is Return on Invested Capital
Investors are increasingly focused on a simple measure: return on invested capital.
If a company spends $100 billion on AI infrastructure, how much extra profit does that investment produce?
If the answer is unclear, the market may apply a lower valuation even if revenue continues to grow.
This is the shift currently taking place.
AI spending itself is no longer automatically bullish.
Investors want evidence that spending converts into durable earnings.
Why Free Cash Flow Is Becoming Critical
Free cash flow is the money left after a company pays for normal operations and capital expenditure.
It matters because it shows how much cash a business can use for buybacks, dividends, debt reduction or new investment.
When AI capex consumes most or all of that cash, shareholders lose flexibility.
Meta’s negative Q3 free cash flow therefore sent a strong signal.
The company may still be financially healthy.
But the AI build-out is becoming expensive enough to change the shape of its finances.
Dilution Is Another Investor Concern
Meta also announced a new class of non-voting Class C shares.
The structure is designed to provide flexibility for acquisitions, employee compensation and investment while preserving Mark Zuckerberg’s voting control.
From an investor perspective, new shares raise another question: dilution.
If AI investment is partly financed through additional equity, existing shareholders own a smaller percentage of the company.
That is another reason markets are starting to scrutinise the funding model, not just the technology.
Why Nvidia Is Becoming Part of the Financing System
The AI industry’s financing structure is becoming increasingly interconnected.
Nvidia is not only selling chips.
It has also invested in AI infrastructure companies and committed to buying capacity from some of them.
Reuters Breakingviews recently described Nvidia as emerging as something like a central bank for the AI economy.
The analogy reflects the company’s growing role in supporting the ecosystem that buys its hardware.
This can keep investment flowing.
It can also create circular relationships.
If suppliers finance customers who then buy more equipment from those suppliers, investors must decide how much demand is truly independent.
Could AI Spending Still Pay Off?
Absolutely.
The bearish case should not obscure the upside.
AI can create new products, improve advertising, reduce labour costs, accelerate coding and automate business processes.
If those gains become large enough, today’s spending may look sensible in hindsight.
Meta’s Muse adoption is one example of the opportunity.
If AI agents become central to consumer and business activity, companies with massive infrastructure could gain a powerful long-term advantage.
The uncertainty is timing.
Investors do not know how quickly usage will convert into high-margin revenue.
Why the Market Reaction Is Rational
Investors are not required to choose between “AI will transform the world” and “AI is a bubble”.
Both technological transformation and financial excess can exist at the same time.
Railways transformed economies and still destroyed many investors.
The internet changed the world and still produced a historic market crash.
The same principle applies to AI.
A revolutionary technology does not guarantee that every investment made around it will generate a good return.
What Could Restore Investor Confidence?
| Signal | Why It Matters |
|---|---|
| Higher AI revenue | Shows infrastructure spending is producing measurable demand. |
| Improving margins | Proves AI products can generate profitable growth. |
| Stronger free cash flow | Reduces concern that capex is consuming the business. |
| Lower borrowing costs | Makes data-centre expansion easier to finance. |
| Long-term enterprise contracts | Provide visibility for infrastructure providers. |
| Slower chip depreciation | Improves the economics of AI hardware investment. |
| Better utilisation | Shows expensive data centres are being used efficiently. |
What Could Make the Sell-Off Worse?
The biggest risk is a mismatch between infrastructure supply and profitable demand.
If companies continue building data centres faster than customers create profitable workloads, utilisation could fall.
That would pressure cloud prices.
Lower prices would reduce returns on expensive infrastructure.
Companies carrying large debts would be hit hardest.
A second risk is technological depreciation.
If new chips make existing hardware obsolete faster than expected, the effective life of AI infrastructure could shorten.
A third risk is weaker enterprise adoption.
Many businesses are experimenting with AI, but not all pilots are producing large financial gains.
Why Enterprise AI Adoption Matters More Than Consumer Hype
Consumer usage can create headlines.
Enterprise spending creates recurring revenue.
The strongest long-term case for AI infrastructure depends on businesses moving from experiments to large production deployments.
That means agents, coding assistants, customer-service systems and industry-specific AI need to produce measurable returns.
If enterprise adoption accelerates, today’s capex may prove justified.
If it stalls, the financial pressure will intensify.
The Political Risk Is Also Rising
AI data centres are increasingly facing opposition over electricity use, water consumption, land and local infrastructure.
That can delay projects and raise costs.
Reuters has reported growing political resistance to data-centre development in the United States as the 2026 midterm elections approach.
This adds another layer of risk.
Even a project with strong financial demand can struggle if it cannot secure power, permits or community approval.
What This Means for Nvidia
Nvidia remains one of the biggest beneficiaries of AI capital spending.
That also makes it exposed to a slowdown.
If hyperscalers, neoclouds and startups reduce expansion plans, accelerator demand could eventually soften.
Nvidia’s current position is extremely strong.
But its customers’ ability to finance future purchases matters.
That is why stress at CoreWeave and other infrastructure companies is relevant to Nvidia investors.
What This Means for Meta
Meta now has to prove that its AI spending creates returns large enough to satisfy both equity and credit investors.
Muse adoption helps the argument.
So does AI-driven advertising performance.
But the spending numbers have reached a scale where investors will demand more than user growth.
They will want evidence of monetisation.
What This Means for CoreWeave and Neoclouds
Neocloud companies face an even harder test.
They do not have Meta’s advertising machine or Microsoft’s software business to support infrastructure spending.
Their ability to grow depends heavily on external financing and long-term customer contracts.
That makes high borrowing costs dangerous.
For these firms, the AI capex backlash can quickly become a liquidity problem rather than simply a valuation problem.
Why Treasuries Rallied
The sell-off also pushed investors towards safer assets.
US Treasury prices rose sharply as technology shares fell.
This is another sign that AI risk is starting to affect broader financial markets.
When investors move from AI-linked stocks into government bonds, the issue has moved beyond one company’s earnings report.
Is the AI Trade Broken?
No.
But it is changing.
The easiest phase of the trade was based on scarcity and excitement.
There were too few GPUs, too little data-centre capacity and enormous demand for anything connected to AI.
The next phase is about economics.
Which companies can turn infrastructure into cash?
Which can borrow cheaply?
Which can keep utilisation high?
Which can survive when hardware prices fall?
These questions will separate strong AI businesses from companies that simply benefited from the boom.
AgizoAI Verdict
The AI capex backlash is not a rejection of artificial intelligence.
It is a demand for financial proof.
Investors are beginning to distinguish between AI spending that creates measurable returns and AI spending that relies mainly on future expectations.
Meta’s $135 billion to $145 billion capital-expenditure plan, negative free cash flow and record credit-risk indicator pushed that debate into the mainstream.
CoreWeave’s financing pressure shows why the issue is even more serious for companies without giant legacy cash flows.
The sell-off therefore marks an important transition.
AI is moving from the “build at any cost” phase into the “prove the return” phase.
The technology race is still accelerating. The capital markets are simply starting to ask who can actually afford to stay in it.
For more analysis, see AgizoAI’s coverage of Anthropic’s frontier-AI economics and OpenAI’s expanding enterprise distribution strategy.


Published by
AgizoAI Editorial Team
AI news, prompt engineering, tool reviews and practical technology coverage from the AgizoAI editorial desk.
Continue reading
Related AI stories

AI Agents Are Entering Bank Accounts — and Banks Cannot Always Tell When They Have Gone Too Far
US banks are blocking third-party AI agents after detecting systems inside customer accounts, including behaviour that appeared to go beyond user instructions.
DeepSeek Raises $15 Billion: China’s AI Challenger Prepares for the Public Markets
DeepSeek is reportedly closing a $15 billion funding round and preparing for a STAR Market IPO. We examine the investors, risks and…
OpenAI Comes to Google Cloud: Why the AI Model War Is Becoming a Distribution War
OpenAI is bringing GPT-6 Astra, GPT-6.1 Sol, GPT-6 Luna and Codex to Google Cloud. We explain why AI competition is becoming a…