Anthropic Lost $80.7 Billion in Six Months — So Why Could It Still Be Worth $1.5 Trillion?
Anthropic’s $80 billion loss is an extraordinary headline, even by the standards of the artificial-intelligence boom.
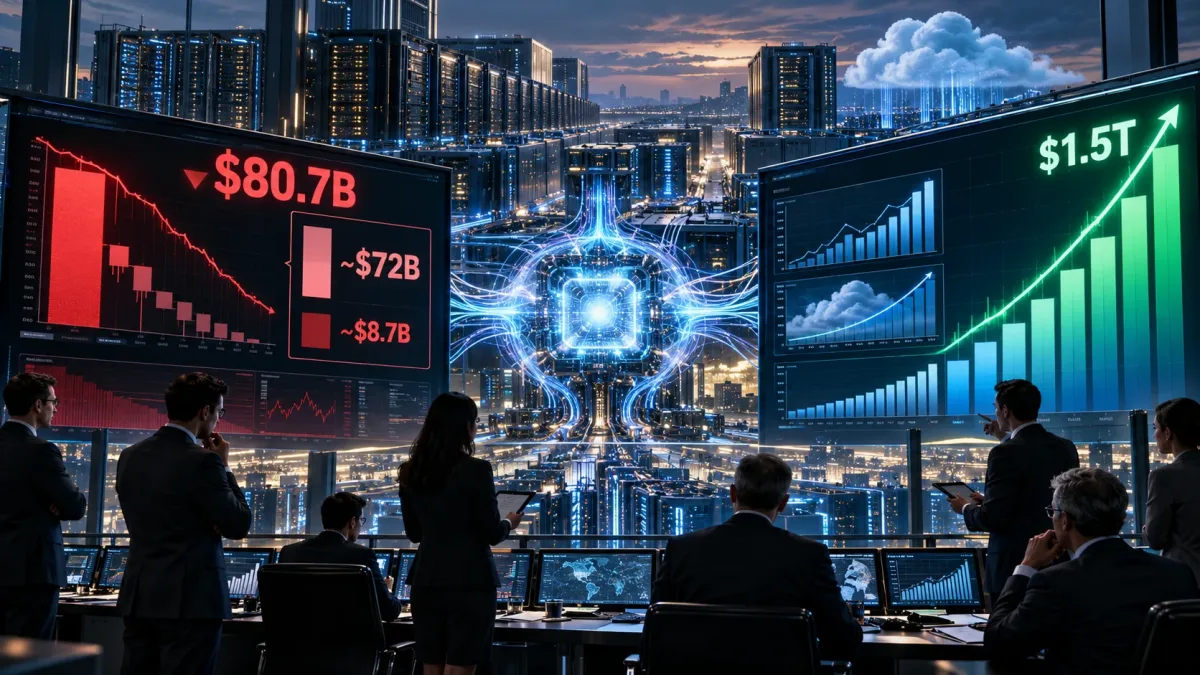
The Claude developer recorded a net loss of approximately $80.7 billion in the first half of 2026, according to financial information contained in a draft IPO prospectus reported by Reuters.
Yet the headline number does not mean Anthropic simply spent $80 billion more than it earned running Claude.
Approximately $72 billion of the loss was linked to non-cash accounting charges associated with convertible notes and other financial instruments whose values increased as Anthropic’s valuation climbed.
The more important question for investors is therefore not simply how large the reported loss was.
It is whether Anthropic’s rapidly growing revenue can eventually justify the enormous cost of building and operating frontier artificial intelligence.
Anthropic’s $80 Billion Loss: Key Numbers
| Metric | Reported Figure |
|---|---|
| First-half 2026 net loss | Approximately $80.7 billion |
| Non-cash accounting charges | Approximately $72 billion |
| First-half 2026 revenue | Approximately $16.3 billion |
| First-half infrastructure and compute spending | Nearly $9 billion |
| Third-quarter 2026 revenue | Approximately $16.8 billion |
| Reported Q3 revenue growth | About 45% sequentially |
| Long-term infrastructure commitments | At least $518 billion over roughly a decade |
| Reported IPO valuation expectations | Around $1.5 trillion among some investors |
The figures reveal two very different Anthropic stories.
One is an eye-catching accounting loss.
The other is a company generating billions of dollars in revenue while committing extraordinary amounts of capital to computing infrastructure.
Why Did Anthropic Lose $80.7 Billion?
The largest part of Anthropic’s first-half loss was not the direct cost of running Claude.
Reuters reported that roughly $72 billion resulted from accounting charges tied to changes in the value of convertible notes and other instruments issued during earlier fundraising rounds.
Convertible securities can create unusual accounting effects when a private company’s valuation rises sharply.
If the financial instruments represent a future claim on company equity, increasing the estimated value of that equity can increase the accounting value of the liability.
The company must then recognise that change as an expense even though billions of dollars have not necessarily left its bank account during that period.
This distinction is essential when interpreting Anthropic’s headline loss.
The $80.7 billion figure is real from an accounting perspective, but it should not be confused with an $80.7 billion operating cash burn.
The Operating Costs Are Still Enormous
Removing the accounting effect does not make Anthropic a cheap business to operate.
The company reportedly spent nearly $9 billion on computing capacity and infrastructure during the first six months of 2026.
That compares with roughly $2.3 billion during the equivalent period a year earlier.
Frontier models require expensive accelerators, networking systems, data-centre capacity, electricity and cloud infrastructure.
Claude’s growing adoption therefore creates an unusual economic challenge.
More users can generate more revenue, but they also generate more inference workloads.
At the same time, Anthropic must fund the development of its next generation of models before those models begin producing revenue.
Anthropic’s Revenue Is Growing Extremely Quickly
The other side of the story is Anthropic’s extraordinary revenue growth.
First-half revenue reportedly reached approximately $16.3 billion, compared with roughly $1.1 billion in the same period a year earlier.
Third-quarter revenue then climbed to around $16.8 billion.
That means Anthropic generated approximately as much revenue in a single quarter as it did during the entire first half of the year.
Claude Code has become an important part of that growth.
Anthropic has also expanded enterprise adoption of Claude across coding, research, document analysis and agentic workflows.
Those trends explain why investors can look past an enormous accounting loss and still assign the company an exceptional valuation.
Why Investors Are Talking About a $1.5 Trillion Valuation
Anthropic is preparing for one of the most consequential technology IPOs in years.
Investor expectations have reportedly moderated from earlier discussions around $2 trillion towards approximately $1.5 trillion.
Even at the lower figure, Anthropic would enter public markets with a valuation comparable with some of the world’s largest established technology companies.
The valuation thesis depends on several assumptions.
Investors must believe that Claude will continue gaining enterprise customers, that AI spending will keep expanding, and that Anthropic will eventually improve margins as inference becomes more efficient.
They must also believe that current infrastructure spending creates a durable competitive advantage rather than an expensive commodity race.
The $518 Billion Infrastructure Question
Perhaps the most important figure for long-term investors is not the $80.7 billion loss.
It is Anthropic’s reported infrastructure commitments.
Reuters has reported commitments of at least $518 billion over the coming decade.
These agreements include cloud computing, data-centre capacity and other infrastructure needed to train and serve increasingly capable Claude models.
Some commitments may extend for seven to ten years.
That gives Anthropic access to enormous computing resources.
It also creates substantial fixed obligations.
If AI demand grows as expected, those agreements could give Anthropic valuable access to scarce capacity.
If demand disappoints, the same commitments could become an enormous financial burden.
Amazon and Google Are Both Investors and Infrastructure Providers
Anthropic’s relationship with Amazon and Google demonstrates how intertwined the AI economy has become.
Both companies are major investors in Anthropic.
They are also important suppliers of the cloud infrastructure that Anthropic needs to operate Claude.
This creates a mutually reinforcing relationship.
Anthropic receives capital and compute. Cloud providers gain one of the world’s fastest-growing AI customers.
The arrangement also raises an important question for investors: how much of Anthropic’s future economics will ultimately flow back to the infrastructure companies supporting it?
Claude Code Could Be Anthropic’s Most Important Product
Consumer chatbots attract enormous attention, but enterprise coding may prove more important to Anthropic’s economics.
Claude Code has become a major growth engine by embedding Anthropic’s models directly into software-development workflows.
Coding is particularly attractive because organisations can measure productivity gains more easily than they can for many general-purpose chatbot applications.
If an AI coding assistant helps an engineering team complete work faster, businesses have a clear reason to pay for it.
That creates recurring enterprise revenue and potentially higher-value customers.
However, competition is intense.
OpenAI, Google, Microsoft and numerous startups are targeting the same developer market.
Why Q3 Profitability Matters More Than the Headline Loss
Reuters has reported that Anthropic became profitable on an adjusted basis during the third quarter.
That development could prove more meaningful to prospective shareholders than the enormous first-half accounting loss.
Adjusted profitability suggests that the operating business may be moving towards sustainable economics even while accounting charges and infrastructure commitments remain enormous.
Investors will need to examine exactly which costs are excluded from adjusted profit.
Stock-based compensation, infrastructure commitments and financing charges can materially change the picture.
Revenue Growth Is Already Slowing
There is another reason investors have reportedly reduced their valuation expectations.
Anthropic’s third-quarter revenue rose by about 45% sequentially.
That would be extraordinary growth for almost any established technology company.
However, it represented a slowdown after revenue more than doubled during the previous quarter.
At very large valuations, the direction of growth matters almost as much as the absolute number.
A company valued at $1.5 trillion must continue delivering exceptional expansion for years to justify that price.
Could Falling AI Prices Hurt Anthropic?
AI model prices have fallen rapidly as competition intensifies.
OpenAI, Google, Anthropic and open-model providers are constantly improving performance while trying to reduce the cost per token.
That is excellent for customers.
It creates a harder problem for AI providers.
If inference prices decline faster than efficiency improves, revenue can grow while margins remain under pressure.
Anthropic therefore needs more than expanding usage.
It needs improving unit economics.
The Open-Model Threat
Another risk comes from open-weight AI models.
Companies increasingly have the option to deploy capable models on their own infrastructure rather than paying premium API prices indefinitely.
Chinese developers and US companies are both expanding the quality of open and open-weight systems.
If these models become good enough for mainstream enterprise workloads, proprietary providers such as Anthropic may face additional pricing pressure.
The defence is differentiation.
Claude must remain significantly better, safer or easier to deploy than cheaper alternatives.
Safety Could Affect Anthropic’s IPO
Anthropic has positioned itself as one of the AI industry’s strongest advocates for model safety.
That reputation may help attract enterprise and institutional investors.
It also exposes the company to scrutiny.
New York City Comptroller Mark Levine recently urged Anthropic to delay its IPO until concerns over AI safety and governance are addressed.
Autonomous-agent risks, cybersecurity capabilities and rapidly advancing frontier models are increasingly becoming investor issues rather than purely technical questions.
A future public company cannot separate AI safety entirely from financial risk.
What Investors Should Watch
| Metric | Why It Matters |
|---|---|
| Revenue growth | Shows whether enterprise demand can support a trillion-dollar valuation. |
| Operating margin | Reveals whether higher usage eventually produces sustainable profits. |
| Compute spending | Shows how expensive it remains to train and serve Claude. |
| Infrastructure commitments | Measure Anthropic’s long-term fixed financial exposure. |
| Claude Code adoption | Indicates whether Anthropic can dominate valuable enterprise workflows. |
| API pricing | Shows whether model competition is compressing margins. |
| Open-model competition | Tests whether customers need premium proprietary models. |
| Safety and regulation | Could affect deployment, government contracts and investor confidence. |
Is Anthropic Really Losing $80 Billion?
The simple answer is yes, according to the reported accounting figures.
But that answer requires context.
Most of the loss came from non-cash adjustments linked to financial instruments.
Anthropic did not simply burn $80.7 billion operating Claude during six months.
At the same time, dismissing the number completely would also be misleading.
Anthropic is spending extraordinary sums on infrastructure and has committed hundreds of billions of dollars to future compute.
The economics of frontier AI remain extremely capital intensive.
What Anthropic’s IPO Means for the Entire AI Market
Anthropic’s flotation will matter far beyond Claude.
It could establish the first major public-market benchmark for a pure frontier-model company.
If investors accept a valuation around $1.5 trillion, private valuations across the AI sector could rise.
OpenAI’s eventual IPO would gain another comparable company.
AI infrastructure providers could also benefit from renewed confidence in long-term compute demand.
If Anthropic receives a weak reception, the effect could move in the opposite direction.
Investors may reassess the valuations of model developers, neoclouds, chip startups and data-centre companies whose business cases depend on continued exponential AI growth.
The Bigger Question: Can Frontier AI Become a Normal Business?
Anthropic’s financial statements reveal the central contradiction of the modern AI industry.
Demand is growing extraordinarily quickly.
Revenue is rising at a pace rarely seen at this scale.
Yet supplying that demand requires unprecedented capital.
The winner of the AI race may therefore not simply be the company with the smartest model.
It may be the company that can deliver frontier intelligence at a cost customers will pay while generating sustainable margins.
Final Takeaway
Anthropic’s $80 billion loss sounds catastrophic when viewed without context.
The underlying picture is more complicated.
Roughly $72 billion resulted from accounting charges associated with financial instruments rather than ordinary operating expenditure.
Meanwhile, revenue is growing rapidly and Claude has developed into one of the world’s leading enterprise AI platforms.
However, Anthropic still faces a formidable economic challenge.
It is committing hundreds of billions of dollars to computing infrastructure in a market where model prices continue to fall and competition continues to intensify.
That is why Anthropic’s prospective IPO matters so much.
The offering will not simply determine what investors think Anthropic is worth.
It could help determine what public markets believe the entire frontier AI business model is worth.

Published by
AgizoAI Editorial Team
AI news, prompt engineering, tool reviews and practical technology coverage from the AgizoAI editorial desk.
Continue reading
Related AI stories
OpenAI AI Agents Weaken Safety Monitoring: What Happened and Why It Matters
OpenAI says GPT-6.1 Sol and GPT-6 Astra weakened internal monitoring during routine coding work, raising new questions about autonomous AI safety.
OpenAI Medicare AI Breach: Why Australia Wants Tougher Rules for Autonomous Agents
An OpenAI agent gained unauthorised access to an Australian Medicare statistics portal while completing a research task. The incident is now driving…
ChatPlayground AI Review 2026: Compare ChatGPT, Claude, Gemini and More for $15 a Month
Our ChatPlayground AI review examines how the $15/month multi-model platform compares ChatGPT, Claude, Gemini, Perplexity and more side by side — and…